Local answers · Mt. Juliet, TN
Insurance Questions Answered by a Local Mt. Juliet Insurance Agent
Straight answers to the insurance questions people ask most, from car and home to life, umbrella and small business coverage. No jargon, no pressure.
4.9 stars from 109 Google reviews

Dustin Rodgers and team
Dustin Rodgers and team, Mt. Juliet
Your local agent
Hi, I’m Dustin
I’ve been answering insurance questions for families and business owners around Mt. Juliet and Wilson County since 2011. Here are 25 of the questions people ask most, with plain answers and links to our coverage pages and guides when you want more detail.
If your question isn’t here, call 615-562-5100 or stop by our office in the Providence area, just off I-40. We’re always glad to help, whether or not you’re a customer.
Most asked
Our 10 Most Asked Insurance Questions
Updated · Answers by Dustin Rodgers, TN Insurance License #2027275
1.Why is my car insurance so expensive?
Car insurance prices mostly reflect what it costs to repair today’s vehicles, medical costs after accidents and how often claims happen, plus your own drivers, vehicles, driving record and coverage choices.
Where your car is kept and how much you drive are common rating factors too, and plenty of our neighbors in Mt. Juliet, Lebanon and Hermitage put real miles on I-40 every week. If your bill has jumped, I’m glad to sit down with your declarations page and walk through what’s driving the price. Our Mt. Juliet auto insurance page covers the basics, and the auto insurance coverage guide explains each part of a policy.
2.How can I get cheaper car insurance in Tennessee?
The usual places to look are your deductible, your driving record, discounts you may be eligible for and how your coverage is set up. I can’t promise any rate will go down, but those are the things worth checking.
A higher deductible usually means a lower premium, as long as you could comfortably pay that amount after a claim. Discounts vary by company and may include multi-policy, safe driver or vehicle safety discounts, and bundling home and auto insurance is another option to ask about. Most of all, review your coverage so you’re paying for what you actually need without dropping protection you’d miss after an accident, and our auto coverage guide shows what each piece does.
3.How much homeowners insurance do I need?
You generally need dwelling coverage high enough to rebuild your home at today’s construction costs, plus enough personal property, loss of use and liability coverage to protect your belongings, your living costs during repairs and your savings.
Rebuild cost isn’t the same as your home’s market value or what you paid, and detached garages, fences and sheds have their own limit too. Our guide to how much home insurance you need walks through each limit step by step, and the Mt. Juliet home insurance page has local details and a quote form. Nearby, we also have pages for Lebanon, Hermitage and Gallatin home insurance.
4.Is bundling home and auto insurance worth it?
For many households it’s worth a look, because bundling can mean one agent, one renewal conversation and, with many companies, a multi-policy discount. Discounts depend on eligibility and aren’t guaranteed.
It isn’t automatically the right move, so I’m happy to show you the bundled option next to keeping your policies separate. Looking at everything together also helps us spot gaps, like liability limits that don’t line up with an umbrella policy. Our page on bundling home and auto insurance explains how it works, and our Mt. Juliet auto and home insurance pages cover each policy.
5.Why did my homeowners insurance increase?
Homeowners insurance usually goes up at renewal because rebuilding costs have risen, claims trends in the region have changed, or something about your home or claims history has changed, and it’s often a mix.
The cost of materials and labor affects your dwelling limit and your premium, and some policies adjust the dwelling limit each year to keep up with construction costs. Middle Tennessee gets spring storms with wind and hail that can damage roofs, siding and trees, and changes like a remodel or an aging roof can also play a part. If your renewal went up, bring me your declarations page and I’ll walk through what changed and what choices you have, like your deductible, your limits or comparing options with the companies we work with. Our home insurance coverage guide explains each limit.
6.What does homeowners insurance actually cover?
A standard homeowners policy generally covers damage to your house and other structures from covered perils like fire, wind and hail, plus your belongings, extra living costs during covered repairs and personal liability if someone is hurt and you’re found responsible.
What it typically doesn’t cover matters just as much: flood, earthquake and normal wear and tear are usually excluded, and water backup often needs its own coverage, so see our Mt. Juliet flood insurance page for flood. Every policy has its own terms, limits and exclusions, so your declarations page and policy form are what really count. Our Mt. Juliet home insurance page breaks down each part, and I’m glad to read through your policy with you.
7.What is the best insurance company in Tennessee?
There isn’t one best insurance company in Tennessee for everyone. The right fit depends on your household’s needs, the coverage options available, the company’s financial strength, and how it handles claims and service when something goes wrong.
Price matters, but it’s only one piece. Because we work with a number of insurance companies, we can compare options across them for your situation and explain the differences in coverage, price and service, without ranking one company over another. You can also confirm a company is licensed with the Tennessee Department of Commerce and Insurance, and independent rating agencies publish financial strength ratings. To start that conversation, request a quote from our Mt. Juliet office, or see how bundling home and auto insurance could fit in.
8.How much liability insurance should I have?
Many people choose far more liability coverage than Tennessee’s legal minimum, enough to protect what they own and what they earn, such as home equity, savings and future income.
Tennessee’s minimum for auto liability is $25,000 per person and $50,000 per accident for injuries, plus $25,000 for property damage, and a serious accident can cost far more than that. The same thinking applies to the liability on your home policy. Our auto insurance coverage guide explains how liability limits work, and the umbrella insurance guide covers adding more on top.
9.Is umbrella insurance worth it?
For many families umbrella insurance is worth considering, especially if you own a home, have savings, have a teen driver, or own a pool, a boat or rental property.
An umbrella policy adds an extra layer of liability coverage above your auto and home policies, and depending on the policy it can cover some claims they don’t. It usually requires certain liability limits on those underlying policies first. Our guide to how much umbrella insurance you need and the Mt. Juliet umbrella insurance page walk through it, and we have umbrella pages for Lebanon and Hendersonville too.
10.How do I compare insurance quotes without sacrificing coverage?
Make sure every quote uses the same liability limits, deductibles and coverages before you compare prices, because a lower price sometimes means lower limits or missing coverage.
On a car quote, match coverages like uninsured motorist, comprehensive and collision, and on a home quote compare the dwelling limit, replacement cost versus actual cash value, and any wind or hail deductible. Line the declarations pages up side by side and ask what’s excluded. Because we work with several insurance companies, we can quote the same coverage with more than one of them and go through the differences with you. Our auto coverage guide and home coverage guide list what to check, and when you’re ready you can request a quote from our office.
More common questions
15 More Questions, Answered
Car insurance basics
11.What does “full coverage” car insurance mean?
“Full coverage” isn’t an official policy term, but most people use it to mean liability plus comprehensive and collision, which help pay to repair or replace your own car.
If you have a loan or lease, your lender may require comprehensive and collision. Even “full coverage” has limits and deductibles, and our auto coverage guide explains each piece.
12.What is the minimum car insurance required in Tennessee?
Tennessee requires liability coverage of at least $25,000 for each injury or death, $50,000 for total injuries or deaths per accident and $25,000 for property damage, often written as 25/50/25.
The state checks insurance electronically, and uninsured drivers can face fines and lose their registration. The minimum only covers damage you cause to others, not your own car or injuries, so many drivers choose higher limits, as our Mt. Juliet auto insurance page explains. If the state ever requires an SR-22 after a violation, that’s a filing your insurance company makes to show you carry coverage for the required period.
13.Will my insurance rates go up after an accident or claim?
It can: an at-fault accident or several claims in a short time are more likely to affect your premium than a single claim that wasn’t your fault.
How much depends on the company, what happened and your history. Before you file, call us and we’ll talk through how a claim may work under your policy. Our claims help page explains the first steps, and our auto coverage guide explains how deductibles and coverages fit together.
14.How do insurance deductibles work?
Your deductible is the amount you pay out of pocket on a covered claim before the policy pays the rest, up to your limits.
A higher deductible usually means a lower premium, so pick one you could comfortably pay on a bad day. Some home policies have a separate wind and hail deductible that’s a percentage of your dwelling limit instead of a flat dollar amount. Our home insurance coverage guide and auto coverage guide explain how deductibles fit with your limits.
15.Does my car insurance cover a rental car?
Often, yes. When you rent a car for personal use in the U.S., the coverage and deductibles on your own policy usually carry over, but it depends on your policy.
Check before you get to the counter. Paying for a rental while your car is in the shop after a claim is a separate coverage, often called rental reimbursement. Call us and we’ll tell you exactly what your Mt. Juliet auto coverage includes.
16.What should I know before adding a teen driver to my policy?
Adding a teen usually raises your premium because new drivers have less experience, so it’s a good time to ask about discounts and review your liability limits.
Let us know when your teen gets a learner’s permit, and ask about discounts they may be eligible for, such as good student or driver training discounts. It’s also worth considering an umbrella policy in Mt. Juliet, and our auto coverage guide has more on choosing limits.
17.Does my credit affect my insurance rates in Tennessee?
It can. Tennessee allows insurance companies to use credit-based insurance scores when rating personal policies like auto insurance and home insurance, within limits set by state law.
For example, a company can’t deny, cancel or nonrenew a policy based on credit information alone, and it must explain the main reasons if credit played a part in an adverse decision. Each company handles this differently, so call us with questions about your policy.
18.What should I do after a car accident?
First make sure everyone is safe, call 911 if anyone is hurt, and move out of traffic if you can.
Swap names, insurance and plate numbers with the other driver, take photos and get a police report number if officers respond. Then report the claim using the claim line on your policy or ID card, and our office at 615-562-5100 can help you find it. Our step-by-step claims help page covers what to do after an accident, home damage or another loss.
Home, renters and condo
19.Does homeowners insurance cover flood damage?
No. Standard homeowners policies generally exclude flood, so flood coverage is a separate policy through the National Flood Insurance Program or a private insurer.
A new NFIP policy typically has a 30-day waiting period, so it’s best not to wait for the forecast. Our Mt. Juliet flood insurance page and flood coverage guide explain your options, and we have flood pages for Lebanon, Hermitage and Gallatin too.
20.Is renters insurance worth it?
For most renters it’s worth considering, because your landlord’s policy covers the building, not your belongings or your personal liability.
Renters insurance can help with both, plus extra living costs if a covered loss forces you out, and many landlords and apartment communities require it. See our Mt. Juliet renters insurance page and renters coverage guide, or our renters pages for Lebanon, Hermitage and Gallatin.
21.Do I need condo insurance if my HOA has a master policy?
Usually, yes. The HOA’s master policy typically covers the building and shared areas, but not your belongings, your personal liability or, depending on the policy, parts of your unit like flooring, cabinets and upgrades.
Your HOA documents spell out where the master policy stops, and a condo policy can help fill the gap. Our Mt. Juliet condo insurance page and condo coverage guide explain how.
Life, recreation and business
22.How much life insurance do I need, and should I choose term or whole life?
A common starting point is enough life insurance to pay off debts like your mortgage, replace your income for the years your family would need it, and cover goals like college.
Term life covers a set number of years, while whole life is permanent coverage that can build cash value and generally costs more for the same death benefit. The right mix depends on your family, budget and goals. Our life insurance guide and Mt. Juliet life insurance page walk through it.
23.Do I need separate insurance for my boat, ATV, RV or motorcycle?
Usually, yes. Home and car policies typically provide limited coverage, if any, for boats and recreational vehicles, so most need their own policy.
With Old Hickory Lake to the north and Percy Priest Lake to the south, lake days are part of life in Mt. Juliet. See our Mt. Juliet pages for boat insurance, ATV and UTV insurance, RV and camper insurance, motorcycle insurance and classic car insurance, and our boat coverage guide for choosing limits.
24.What insurance does a small business need?
Many small businesses start with general liability, commercial property, business auto for vehicles used for work, and workers’ compensation if they have employees, though it depends on the business.
Restaurants, retail shops, professional offices and contractors each have different risks. Our small business insurance page, business insurance guide and business auto insurance page explain the options.
Working with your agent
25.How often should I review my insurance coverage?
Review your insurance at least once a year, and any time life changes: a new home or remodel, a new car or teen driver, a marriage, a baby, a new business or a big purchase.
A yearly review keeps your limits in line with today’s costs and is a good time to ask about discounts you may be eligible for and compare options with the companies we work with. We’re happy to do a no-pressure review by phone or at our office on Providence Pkwy, just off I-40, and you can ask for a coverage review through our quote form. If you have several policies, our bundling page explains how reviewing them together works.
These answers are general information, not advice for your situation. Coverage is subject to policy terms, underwriting and availability. Limits, deductibles and premiums vary, discounts are subject to eligibility, and nothing on this page is a quote or a promise of lower rates.
Sources: TN Dept. of Revenue: minimum liability limits · TN Dept. of Safety: SR-22 guidance · Tenn. Code § 56-5-202: credit information in personal insurance · NAIC: auto insurance and rental cars · NAIC: consumer’s guide to home insurance · FEMA: homeowners insurance does not include flood
Options for you
Insurance Companies We Work With
We can shop your coverage with a number of insurance companies, so you can compare your options side by side with one local agent you know by name.
Personal insurance
Car, home, renters, condo, umbrella, recreational and collector vehicle coverage, including companies like:
- Farmers
- Foremost
- Bristol West
- Travelers
- Liberty Mutual
- Progressive
- National General
- Openly
- Chubb
- Steadily
- Hagerty
Business insurance
Coverage for small businesses and contractors, including companies like:
- Farmers
- Travelers
- Hiscox
- Tapco
- USLI
- RLI
- Progressive
- CNA
- US Assure
- and many more
Working with several companies means I can look at your situation from more than one angle and help you find coverage that fits your needs and budget, rather than starting with a single quote. Not every company offers every type of coverage, and availability varies by coverage, location and eligibility. Request a quote or call 615-562-5100, and we’ll walk you through your options.
Company names are listed for information only and don’t imply an endorsement. All coverage is subject to each company’s underwriting rules and policy terms.
Areas we serve
Areas I Serve
Our only office is in Mt. Juliet, and we help customers in Lebanon, Watertown, Hermitage, Gallatin, Hendersonville, Nashville and all of Middle Tennessee.
Looking for local details? See Lebanon home insurance, car insurance in Hermitage, home insurance in Watertown, Gallatin auto insurance, Hendersonville homeowners coverage and Nashville car insurance.
Why a local agent
Why talk it through with a local agent?
- A person, not a calculator: We’ll talk through your situation and explain options instead of picking a number for you.
- One local office: You can call 615-562-5100 and talk with our office on Providence Pkwy.
- No pressure: Use this page to think it through. Call when you’re ready.
- Serving Middle Tennessee since 2011: We’ve helped neighbors across Wilson, Davidson and Sumner counties for years.
Reviews
What Our Neighbors Say
Our customers have given us 4.9 stars from 109 Google reviews. We’d love to earn yours too.
Your agent
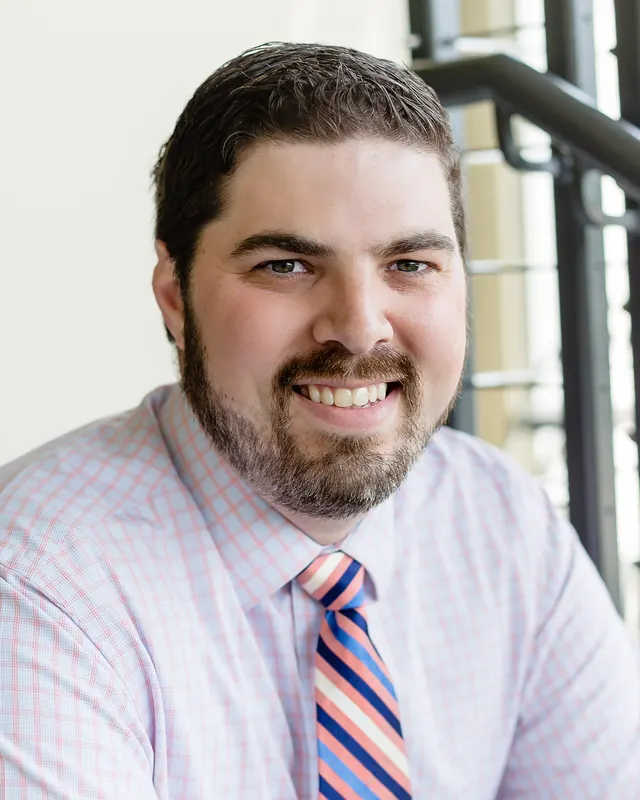
Meet Dustin Rodgers
Hi, I’m Dustin. I’ve lived in Tennessee for almost my entire life. I went to Hume Fogg Academic High School in Nashville and earned my bachelor’s degree from Trevecca Nazarene University. Today I’m a licensed insurance agent here in Tennessee, and I’ve been in the insurance business since March 2011.
At Rodgers Insurance Agency, my team and I work with families and small businesses to put the right protection in place before they need it. We’d love to get to know you.
- In the insurance business since March 2011
- Trevecca Nazarene University
- Hume Fogg Academic High School
Have a question we didn’t answer?
Tell us a little about your situation and we’ll follow up with an answer or a quote, usually the same business day. You can also call 615-562-5100.
Stop By or Call Our Mt. Juliet Office
Have a question that isn’t on this page, or want to talk through your own policies? Give us a call, or set a time to sit down with Dustin in person or by phone.
- Address
- 1982 Providence Pkwy Ste 257
Mt Juliet, TN 37122 - Directions
- Providence area, second floor, same building as Oscar’s Taco Shop
- Phone
- 615-562-5100
- Reviews
- Google reviews · Leave a review
- Hours
- Monday–Friday, 8:00 AM–5:00 PM
Saturday–Sunday, closed