Condo insurance · Mt. Juliet, TN
Mt. Juliet Condo Insurance That Starts Where Your HOA Policy Stops
Your association insures part of the building. The rest, from your cabinets to your couch, is usually up to you. I’m Dustin Rodgers, and I’ll help you sort out which is which.

Dustin Rodgers and team
Local condo insurance help from our Mt. Juliet office
Your local agent
Condo coverage, explained by someone down the road
Buying a condo or townhome in Mt. Juliet comes with a stack of HOA paperwork, and somewhere in it is the master policy. That policy matters, because it decides where the association’s coverage ends and where yours needs to begin. Some master policies cover only the shell of the building; others reach inside to fixtures and finishes. Bring me your bylaws or the master policy summary, and we’ll walk through it together, in plain language, before you pick your own limits.
Coverage
What a Condo Unit Owner Policy Can Cover
A condo policy (often called an HO-6) is built around your unit and your responsibilities under the HOA documents. Common parts include:
-
Walls-in coverage
Can help repair the parts of your unit the association doesn’t insure, such as flooring, cabinets, countertops and improvements you or a past owner added.
-
Personal property
Can help replace your furniture, clothes, electronics and other belongings after a covered loss, at home or, in many cases, away from it.
-
Loss assessment
Can help with your share of a special assessment the association charges owners after a covered loss to common areas, up to the limit you choose.
-
Loss of use
Can help pay for a hotel or other housing, plus extra costs, if a covered loss makes your unit unlivable during repairs.
-
Personal liability
Can help if you’re found responsible for someone’s injury or for damage you cause, like water from your unit leaking into the neighbor’s below.
-
Medical payments to others
Can help with a guest’s medical bills after an injury in your unit, regardless of fault, up to a smaller limit.
Condo coverage depends on your HOA documents, the policy you choose and underwriting. Flood is not covered by a standard condo policy. Coverage is subject to policy terms, underwriting and availability. Limits, deductibles and premiums vary, and nothing on this page is a quote.
Options
Questions Worth Asking About Your Condo
Every association writes its documents a little differently. These are the details I like to check with condo owners:
Discounts and coverages are subject to eligibility, may vary by state, and are not available on every policy.
- Whether the master policy is ’bare walls’ or includes original fixtures and finishes
- The master policy deductible, and how the HOA can pass it to an owner after a loss
- Loss assessment limits that line up with that deductible
- Water backup coverage for drains and sewer lines, which may be excluded unless added
- Upgrades you’ve made since closing, so your walls-in limit keeps up
Around Mt. Juliet
Condo and Townhome Living in Mt. Juliet
Condos and townhomes in Mt. Juliet can put you close to I-40, Providence and the WeGo Star commuter rail without the yard work. The tradeoff is shared walls and shared decisions, which is why the HOA master policy is the first document I ask to see.
Shared walls also mean shared water lines. A leak that starts in one unit can travel to the next, so liability coverage and a clear answer on who insures the drywall are worth having before anything drips.
Flood isn’t part of a standard condo policy. If your building sits low or near a creek, ask whether the association carries flood coverage, and whether a separate policy for your unit and belongings makes sense.
Sources: Washington Insurance Commissioner: how condo insurance works · Maryland Insurance Administration: condo insurance FAQs · WeGo Public Transit: WeGo Star commuter train · FEMA FloodSmart: buying a flood policy
Read the master policy first
The association’s master policy and bylaws decide what you need to insure. Ask your HOA manager for the current certificate of insurance and the deductible, then we can choose your walls-in and loss assessment limits to match.
Areas we serve
Areas I Serve
I work with condo and townhome owners in Mt. Juliet (37122 and 37138), Hermitage, Lebanon, Gallatin, Hendersonville, Watertown and across Middle Tennessee.
Our office is in the Providence area, just off I-40 at Mt. Juliet Rd, so it’s an easy stop whether you’re coming from Lebanon Rd, Hermitage or the lake side of town.
I also work with neighbors just down the road: Hermitage condo and townhome coverage, condo insurance in Lebanon, Nashville condo insurance and condo and townhome coverage in Gallatin.
Why a local agent
Why Condo Owners Call a Local Agent
- We read the HOA paperwork with you: so your limits match what the association actually covers.
- Plain answers: no jargon about ’bare walls’ or ’single entity’ without an explanation.
- Condo and auto in one place: we can look at both policies, plus an umbrella, in one conversation.
- Help after a leak or loss: my office can help you understand the next steps with your claim.
- Close by: we’re on Providence Pkwy, a few minutes from most Mt. Juliet communities.
Reviews
What Mt. Juliet Neighbors Say
Condo owners, townhome owners and longtime neighbors have shared what it’s like to work with my office. Read their reviews on Google, or leave one of your own.
Your agent
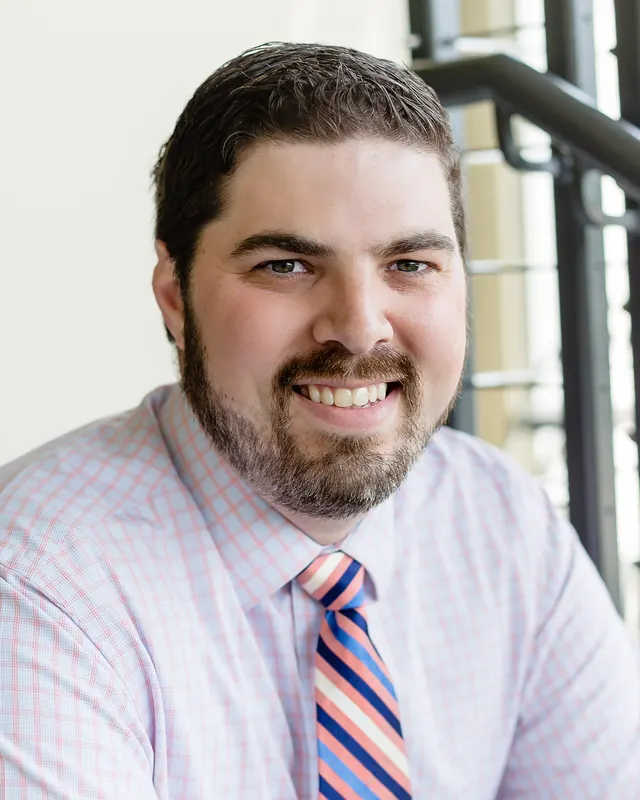
Meet Dustin Rodgers
Hi, I’m Dustin. I’ve lived in Tennessee for almost my entire life. I went to Hume Fogg Academic High School in Nashville and earned my bachelor’s degree from Trevecca Nazarene University. Today I’m a licensed insurance agent here in Tennessee, and I’ve been in the insurance business since March 2011.
At Rodgers Insurance Agency, my team and I work with families and small businesses to put the right protection in place before they need it. We’d love to get to know you.
- In the insurance business since March 2011
- Trevecca Nazarene University
- Hume Fogg Academic High School
FAQ
Mt. Juliet Condo Insurance FAQs
Updated
What’s the difference between my HOA master policy and my condo policy?
The master policy usually covers the building’s structure and common areas, like roofs, hallways and the clubhouse. Your condo policy is meant for what the association doesn’t cover, which can include your interior, your belongings and your personal liability. The HOA documents spell out where that line is, so we start there.
What does ’walls-in’ coverage mean?
It’s the part of a condo policy that can help repair the inside of your unit, such as flooring, cabinets, fixtures and improvements, when the master policy doesn’t. How much you need depends on whether your association’s policy is ’bare walls’ or includes original finishes.
What is loss assessment coverage?
If a covered loss damages common property and the association’s insurance doesn’t pay it all, the HOA may charge each owner a share. Loss assessment coverage can help with your share, up to the limit you choose and subject to the policy terms. Some policies treat assessments for the master deductible differently, so we check the wording.
My HOA covers the building. Do I still need condo insurance?
Usually, yes. Even when the association insures the structure, your furniture, clothing, electronics and personal liability generally aren’t covered by the master policy. Many lenders also require owners to carry their own policy. We’ll look at what applies to your unit.
If water from my unit damages the unit below, who pays?
It depends on what caused the leak, your HOA documents and the policies involved. Your condo policy’s liability coverage may help if you’re found responsible, and the master policy may respond to parts of the building. It’s a good question to sort out before a pipe ever breaks.
Does condo insurance cover flood?
No. Standard condo policies generally exclude flood. Flood insurance is a separate policy, and a new National Flood Insurance Program policy typically has a 30-day waiting period before it starts, with limited exceptions. Ask whether your association carries flood coverage for the building, too.
I rent out my condo. Does that change my coverage?
It can. Renting to a long-term tenant or to short-term guests may call for different coverage than living there yourself, and many HOAs have their own rental rules. Tell me how the unit is used so we can look at the right type of policy.
Can I bundle condo and auto insurance?
Many condo owners keep their condo and auto policies with one agent so they can be reviewed together. Depending on eligibility, a multi-policy discount may be available. We’ll look at what applies before you change anything.
What should I have ready for a condo quote?
Your unit address, the year the building was built, the HOA master policy summary or certificate of insurance, any upgrades you’ve made and your current declarations page if you have one. Then call 615-562-5100 or use the form on this page.
Get a Mt. Juliet Condo Insurance Quote
Call 615-562-5100 or use the form below. If you have it, send the HOA master policy summary or certificate of insurance; it makes the conversation much faster.
Stop By or Call Our Mt. Juliet Office
Have a question about condo insurance or anything else on your policies? Give us a call, or set a time to sit down with Dustin in person or by phone.
- Address
- 1982 Providence Pkwy Ste 257
Mt Juliet, TN 37122 - Directions
- Providence area, second floor, same building as Oscar’s Taco Shop
- Phone
- 615-562-5100
- Reviews
- Google reviews · Leave a review
- Hours
- Monday–Friday, 8:00 AM–5:00 PM
Saturday–Sunday, closed