Flood insurance · Lebanon, TN
Flood Insurance for Lebanon Homes, Condos and Renters
Heavy rain and local creeks are part of life in Wilson County. Your home or renters policy generally won’t cover flood, so we can look at your address and talk through whether a flood policy makes sense.

Dustin Rodgers and team
Serving Lebanon from our Mt. Juliet office
Your local agent
Is flood coverage worth a look in Lebanon?
Lebanon has several creeks, including Bartons Creek and Sinking Creek, and like the rest of Middle Tennessee it sees heavy spring rain. Standard homeowners and renters policies generally don’t include flood, which surprises a lot of people. Flood insurance is a separate policy, and a new one usually needs 30 days before it takes effect. A short quote conversation can help you check your flood zone, understand building and contents coverage, and decide whether a policy makes sense for you.
Coverage
What Lebanon Flood Insurance Can Cover
A Lebanon flood policy is really two coverages in one: the structure and your belongings, each carrying its own limit and deductible. Depending on how it’s set up, that can mean:
-
The structure
Can help repair the foundation, walls, electrical and plumbing systems, HVAC, water heater and built-in appliances after a covered flood.
-
What’s inside
Can help with furniture, clothing, electronics and a washer and dryer. Renters and condo owners can buy contents coverage on its own.
-
Cleanup and debris
Can help with removing flood debris from the insured property, within the policy’s limits.
-
Protecting the property
May help with certain costs to protect insured property when a flood is imminent, like sandbags, subject to terms.
-
Detached garage
Building coverage can extend to a detached garage within the policy’s terms.
-
Beyond the NFIP
Where available, private flood policies may offer different limits or add-ons. Each one reads differently, so we compare them line by line.
Any flood coverage is subject to the policy’s terms, eligibility and availability. Belongings stored below grade, things in the yard and, with the NFIP, the cost of staying somewhere else while you repair are generally left out. Coverage is subject to policy terms, underwriting and availability. Limits, deductibles and premiums vary, and nothing on this page is a quote.
Options
Questions We’ll Work Through
A Lebanon flood policy comes down to a handful of choices:
Discounts and coverages are subject to eligibility, may vary by state, and are not available on every policy.
- The house itself, the things in it, or both
- An NFIP policy or a private flood policy, where available
- Separate building and contents deductibles
- Whether you have an elevation certificate, and whether one would help
- Your start date, given the 30-day waiting period
Around Lebanon
Flood Risk in Lebanon
Bartons Creek and Sinking Creek both run through Lebanon. Heavy rain, creeks and lake levels all affect where water collects, and FEMA’s flood maps are drawn with that kind of information in mind.
A flood zone is a useful starting point, not the whole picture. Properties outside high-risk zones can also see water from a heavy rain or a drainage problem, and lenders generally require flood insurance only in high-risk zones. We can look up your address together, with no pressure either way.
FEMA’s Community Status Book lists the City of Lebanon as a participating community in the National Flood Insurance Program, so NFIP policies can be written for eligible properties in the city. If your address is outside the city limits, Wilson County is its own NFIP community.
Sources: FEMA: NFIP Community Status Book, Tennessee · U.S. Army: Lebanon partners with Corps to study flood risk in the Bartons Creek watershed · FEMA Flood Map Service Center
Know about the 30-day wait
With the National Flood Insurance Program, a brand-new policy generally doesn’t start until 30 days after you buy it. Mortgage-related purchases (a new, larger, extended or renewed loan) are an exception, and some properties that FEMA newly maps into a high-risk zone get a one-day wait. So if you’re curious about flood coverage, it’s simplest to ask while there’s no rush.
Sources: FEMA FloodSmart: buying a flood policy · FEMA: 30-day waiting period for a new NFIP flood policy · FEMA: homeowners insurance does not include flood
Areas we serve
Areas I Serve
I work with homeowners, renters and property owners in Lebanon (37087 and 37090), Watertown, Mt. Juliet and across Wilson County.
Our only office is on Providence Pkwy in Mt. Juliet, just off I-40 at Mt. Juliet Rd, a straight shot west from Lebanon. Many questions can be handled by phone or email, and you’re always welcome to stop by.
Closer to Hermitage? See flood coverage in Hermitage.
Why a local agent
Why Lebanon Families Ask Us About Flood
- We check your address with you: flood zone, map panel and elevation questions in plain English.
- Good timing: we’ll set a start date with the waiting period in mind.
- Flood beside your other policies: we’ll see how it fits with your home, condo or renters coverage.
- Claim questions: if water gets in, call us and we’ll help you figure out where to start.
- Wilson County neighbors: we know the creeks and low spots between Mt. Juliet and Lebanon.
Reviews
What Lebanon Neighbors Say
Lebanon and Wilson County clients have written about their experience with my office on Google. Take a look, and add your own if we’ve helped you.
Your agent
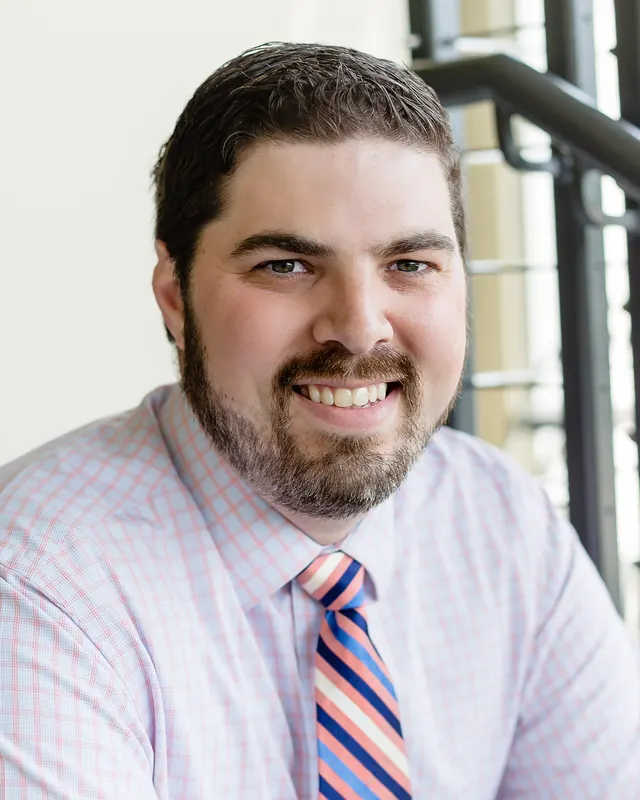
Meet Dustin Rodgers
Hi, I’m Dustin. I’ve lived in Tennessee for almost my entire life. I went to Hume Fogg Academic High School in Nashville and earned my bachelor’s degree from Trevecca Nazarene University. Today I’m a licensed insurance agent here in Tennessee, and I’ve been in the insurance business since March 2011.
At Rodgers Insurance Agency, my team and I work with families and small businesses to put the right protection in place before they need it. We’d love to get to know you.
- In the insurance business since March 2011
- Trevecca Nazarene University
- Hume Fogg Academic High School
FAQ
Lebanon Flood Insurance FAQs
Updated
Is Lebanon in the National Flood Insurance Program?
Yes. FEMA’s Community Status Book lists the City of Lebanon as a participating NFIP community, which means NFIP flood policies are available for eligible properties in the city. Unincorporated Wilson County participates separately. Status can change, so we’ll confirm it when we quote.
How do I find out if my Lebanon address is in a flood zone?
Search your address on FEMA’s Flood Map Service Center, or ask the City of Lebanon’s planning or engineering staff. I’m glad to look it up with you and explain what the zone means for your options.
My house isn’t near Bartons Creek. Do I still need flood insurance?
It’s your decision, and a quick conversation can help. Heavy rain and drainage can affect homes that aren’t next to a creek, and properties outside high-risk zones can still have flood losses. Lenders generally only require flood insurance in high-risk zones, so many owners decide for themselves.
How long before a new flood policy starts?
Plan on roughly a month. The NFIP generally uses a 30-day waiting period, though a policy bought alongside a new or refinanced mortgage can start sooner, and some newly mapped high-risk properties wait just one day. Private flood policies set their own timing.
Does flood insurance cover my basement?
Coverage in basements is limited. Building coverage can include certain items, like a furnace, water heater or electrical panel, but most finished walls, flooring and belongings in a basement aren’t covered under NFIP policies. Private policies vary.
I’m buying a home near downtown Lebanon. When should I ask about flood?
Before you make an offer, if you can. Ask the seller for an elevation certificate and any flood history, and look up the flood zone. If the lender will require flood insurance, the 30-day wait usually doesn’t apply to a policy bought with the new mortgage.
Can I buy flood coverage if I rent in Lebanon?
Yes. Renters can buy contents-only flood coverage for their belongings. The landlord is responsible for insuring the building itself.
What is an elevation certificate, and do I need one?
It’s a form completed by a licensed surveyor or engineer showing your building’s elevation compared with the expected flood height. It isn’t always required, but it can help with rating some policies and with map amendment requests. A seller or builder may already have one.
What does a flood policy not cover?
Vehicles, money and important papers, most of what’s kept in a basement, and outdoor items like fences, decks, pools and landscaping are usually not covered. NFIP policies also don’t pay for a temporary place to live. Private flood forms vary.
What information helps with a Lebanon flood quote?
The address, the type of foundation, about when the home was built, how many levels it has, and an elevation certificate if one was ever done. Then give us a call at 615-562-5100 or send the form.
Get a Lebanon Flood Insurance Quote
Phone 615-562-5100 or fill out the form below. If you know whether the home is on a slab or crawlspace, about how old it is, and whether a surveyor ever did an elevation certificate, bring that along.
Stop By or Call Our Mt. Juliet Office
Have a question about flood insurance or anything else on your policies? Give us a call, or set a time to sit down with Dustin in person or by phone.
- Address
- 1982 Providence Pkwy Ste 257
Mt Juliet, TN 37122 - Directions
- Providence area, second floor, same building as Oscar’s Taco Shop
- Phone
- 615-562-5100
- Reviews
- Google reviews · Leave a review
- Hours
- Monday–Friday, 8:00 AM–5:00 PM
Saturday–Sunday, closed