Home coverage guide · Middle Tennessee
How Much Home Insurance Do I Need?
Your home policy has several limits, not one. This guide walks through each so you know what to ask.

Dustin Rodgers and team
Dustin Rodgers and team, Mt. Juliet
Your local agent
The short answer
Most people need enough dwelling coverage to rebuild their home at today’s costs, enough personal property coverage to replace their things and enough liability to protect what they’ve worked for. The right amounts depend on your home and your household. A local agent can help you check each one.
Coverage
Sizing your home insurance, step by step
Work through these for your home insurance. Rough answers are fine to start.
-
1. Dwelling: cost to rebuild
Base it on what it would cost to rebuild your home, not its market value or what you paid.
-
2. Other structures
Detached garages, fences and sheds have their own limit. Check it covers what’s on your lot.
-
3. Personal property
Walk through your home and estimate what it would cost to replace your things.
-
4. Loss of use
Think about how long repairs might take and what it would cost to live elsewhere.
-
5. Liability
Consider what you’d want protected if someone sued you. Many people add an umbrella.
-
6. Gaps to ask about
Flood, water backup, valuables and code upgrades often need their own coverage.
This guide is general information, not advice for your situation. Coverage is subject to policy terms, underwriting and availability. Coverage is subject to policy terms, underwriting and availability. Limits, deductibles and premiums vary, and nothing on this page is a quote.
Options
What to gather before you call about home insurance
Having these nearby makes a home insurance review quicker.
Discounts and coverages are subject to eligibility, may vary by state, and are not available on every policy.
- Your current declarations page
- Your home’s year built, square footage and updates
- Your roof’s approximate age
- A rough list of valuables
Around Middle Tennessee
What people often miss with home insurance
Dwelling coverage is meant to rebuild, so market swings in home prices don’t tell you much. Local building costs and your home’s features matter more.
Policies settle claims differently. Replacement cost and actual cash value can lead to very different payouts, so ask which yours uses.
Sources: NAIC: homeowners insurance topic page · NAIC: actual cash value vs. replacement cost coverage · FEMA: homeowners insurance does not include flood
Flood is separate
Standard homeowners policies generally exclude flood. A new NFIP flood policy typically has a 30-day waiting period.
Areas we serve
Areas I Serve
We help customers in Mt. Juliet, Lebanon, Watertown, Hermitage, Gallatin, Hendersonville, Nashville and all of Middle Tennessee.
Our office is in Mt. Juliet, just off I-40 at Mt. Juliet Rd. You can reach us by phone, email or in person.
Why a local agent
Why talk it through with a local agent?
- A person, not a calculator: We’ll talk through your situation and explain options instead of picking a number for you.
- One local office: You can call 615-562-5100 and talk with our office on Providence Pkwy.
- No pressure: Use this page to think it through. Call when you’re ready.
- Serving Middle Tennessee since 2011: We’ve helped neighbors across Wilson, Davidson and Sumner counties for years.
Reviews
What Our Neighbors Say
Our customers have given us 4.9 stars from 109 Google reviews. We’d love to earn yours too.
Your agent
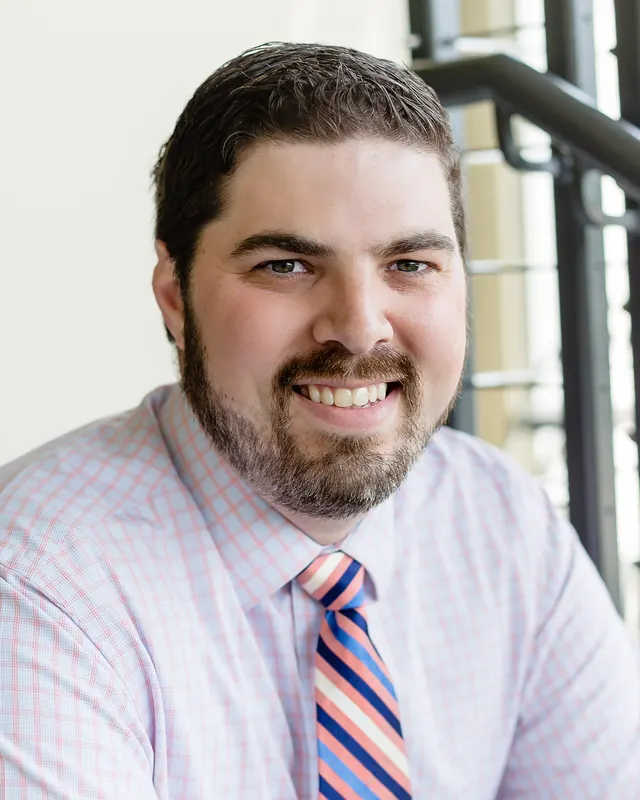
Meet Dustin Rodgers
Hi, I’m Dustin. I’ve lived in Tennessee for almost my entire life. I went to Hume Fogg Academic High School in Nashville and earned my bachelor’s degree from Trevecca Nazarene University. Today I’m a licensed insurance agent here in Tennessee, and I’ve been in the insurance business since March 2011.
At Rodgers Insurance Agency, my team and I work with families and small businesses to put the right protection in place before they need it. We’d love to get to know you.
- In the insurance business since March 2011
- Trevecca Nazarene University
- Hume Fogg Academic High School
FAQ
Middle Tennessee Home Coverage Guide FAQs
Updated
Should my dwelling limit match my home’s market value?
Not necessarily. Dwelling coverage is about rebuilding cost, which can be higher or lower than market value.
What is replacement cost?
Replacement cost pays to repair or replace without taking depreciation off, subject to the policy terms. Actual cash value subtracts depreciation.
How much personal property coverage do I need?
Enough to replace what you own. A room-by-room estimate or a video inventory helps.
How much liability do I need?
It depends on what you want to protect. Many people add an umbrella for more.
Does homeowners cover flood?
No. Flood is a separate policy.
What is ordinance or law coverage?
It can help with the extra cost of meeting current building codes after a covered loss, which matters for older homes.
Do I need to update my limits after a remodel?
Yes. Tell us about major updates so your dwelling limit keeps up.
How often should I review my home policy?
At least once a year, and any time you remodel, buy valuables or change how you use the home.
Can you help me check my limits?
Yes. Call 615-562-5100 and have your declarations page handy.
Questions about your home insurance?
Tell us a little about your situation and we’ll follow up about your home insurance, usually the same business day.
Stop By or Call Our Mt. Juliet Office
Have a question about home coverage guide or anything else on your policies? Give us a call, or set a time to sit down with Dustin in person or by phone.
- Address
- 1982 Providence Pkwy Ste 257
Mt Juliet, TN 37122 - Directions
- Providence area, second floor, same building as Oscar’s Taco Shop
- Phone
- 615-562-5100
- Reviews
- Google reviews · Leave a review
- Hours
- Monday–Friday, 8:00 AM–5:00 PM
Saturday–Sunday, closed